Correction (2026-10-06): The +115% trend-filter figure below left out trading fees and was measured on the same data used to choose the 50-day setting. Our own out-of-sample check, after fees, found the filter lost less than simply holding (−36% vs −52% median per coin), but it still lost. Lines like "'X' leads on auc" show the best of many coin-flip results, not a real edge. The grid-suitability result was also misread: the score ranks coins backwards, so the coins it rated best lost the most.
The Lab ran 7 experiments across 6 research threads this cycle (2026-09-14 → 2026-09-21) on the idle GPUs — every verdict below is published as the data said it, wins, losses and coin-flips alike. No cherry-picking.
Confidence-gated trading sim
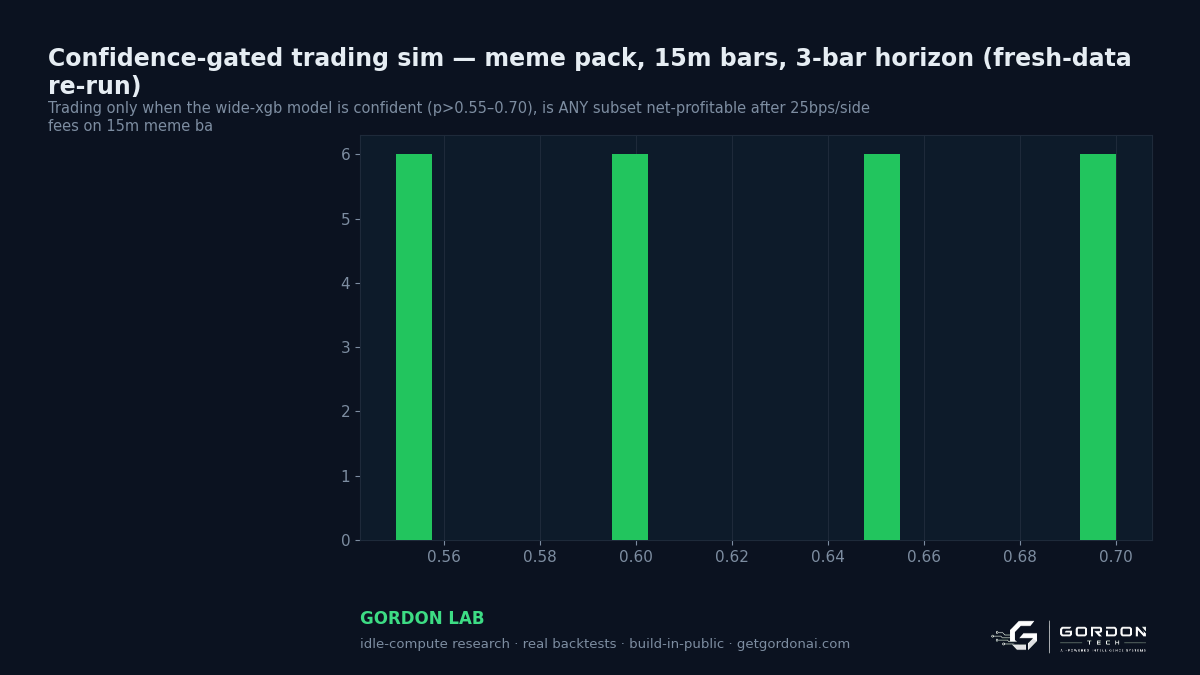
- meme pack, 15m bars, 3-bar horizon (fresh-data re-run) — NO tradeable subset after 25bps/side fees — best cell (short @ p>0.65) still nets -38.8 bps/trade
- broad pack, 15m bars, 3-bar horizon (fresh-data re-run) — NO tradeable subset after 25bps/side fees — best cell (long @ p>0.7) still nets -26.4 bps/trade
Are calm or wild coins easier to predict?
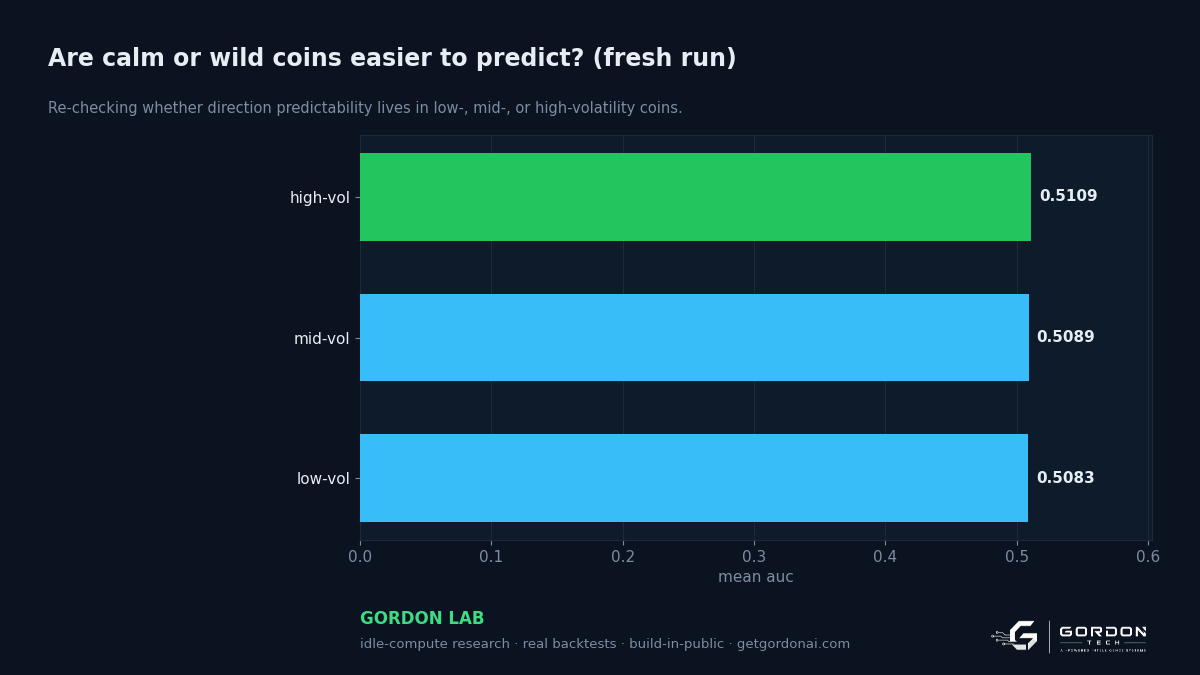
- run of 2026-09-14 — 'high-vol' leads on mean_auc: +0.511
Which crypto coins can a simple ML model actually predict?
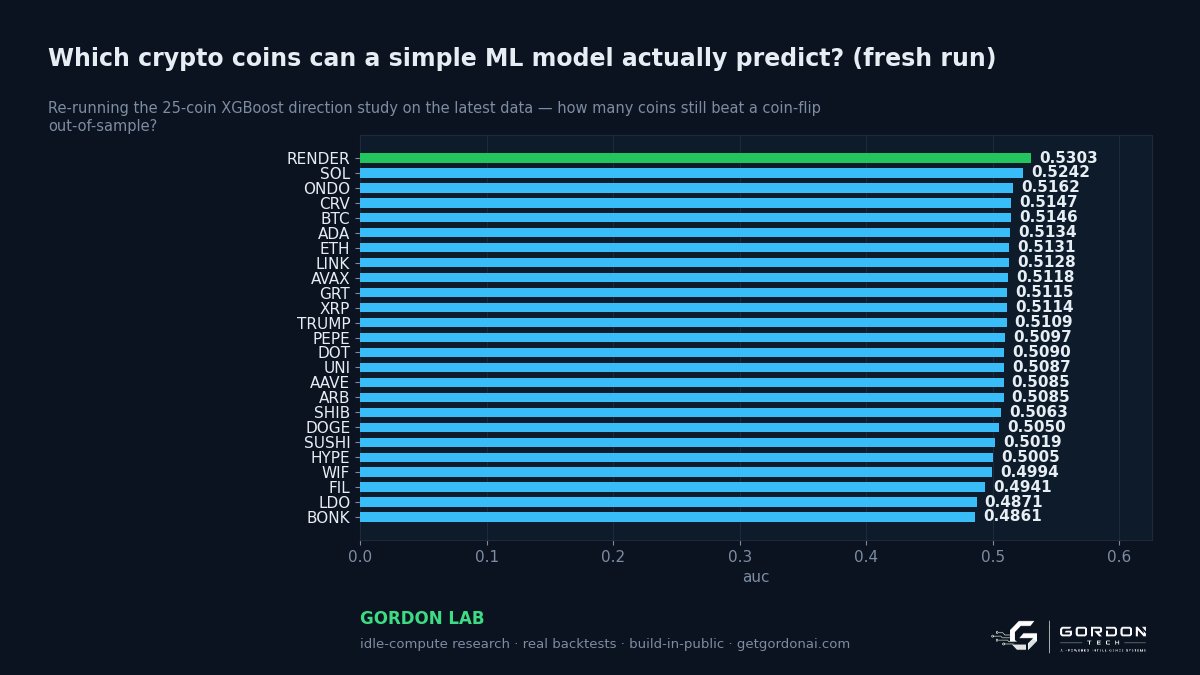
- run of 2026-09-15 — 'RENDER' leads on auc: +0.530
Does crypto direction get more predictable at longer horizons?
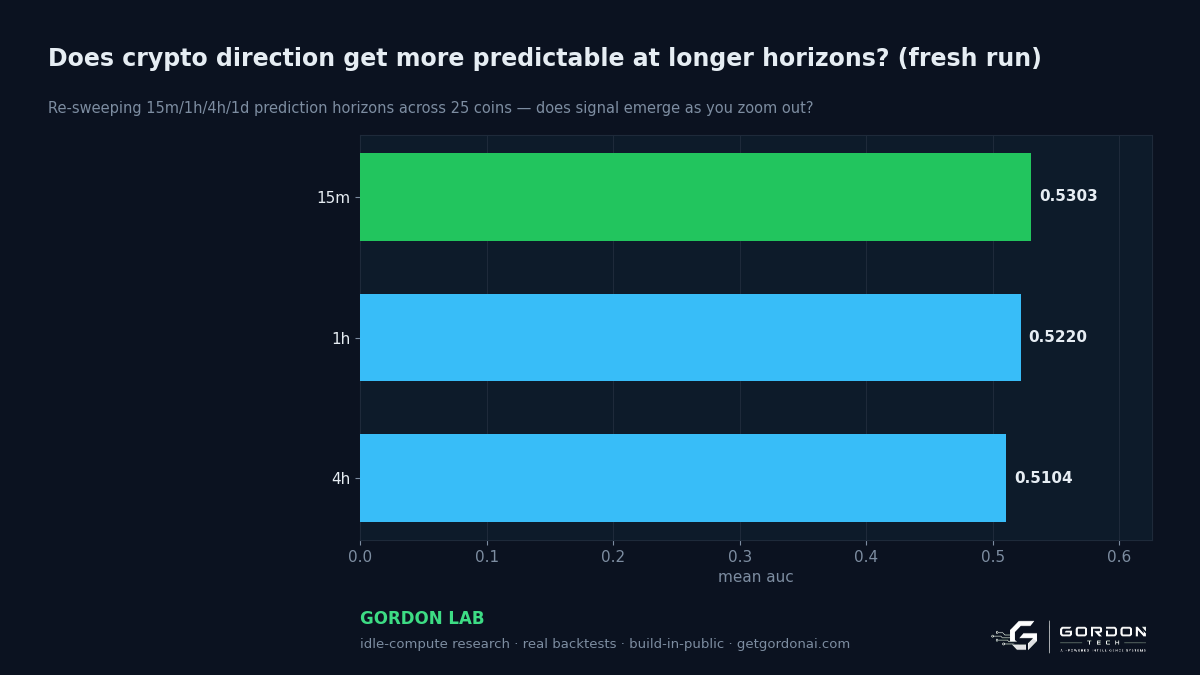
- run of 2026-09-15 — '15m' leads on mean_auc: +0.530
Which coins are actually good for grids?
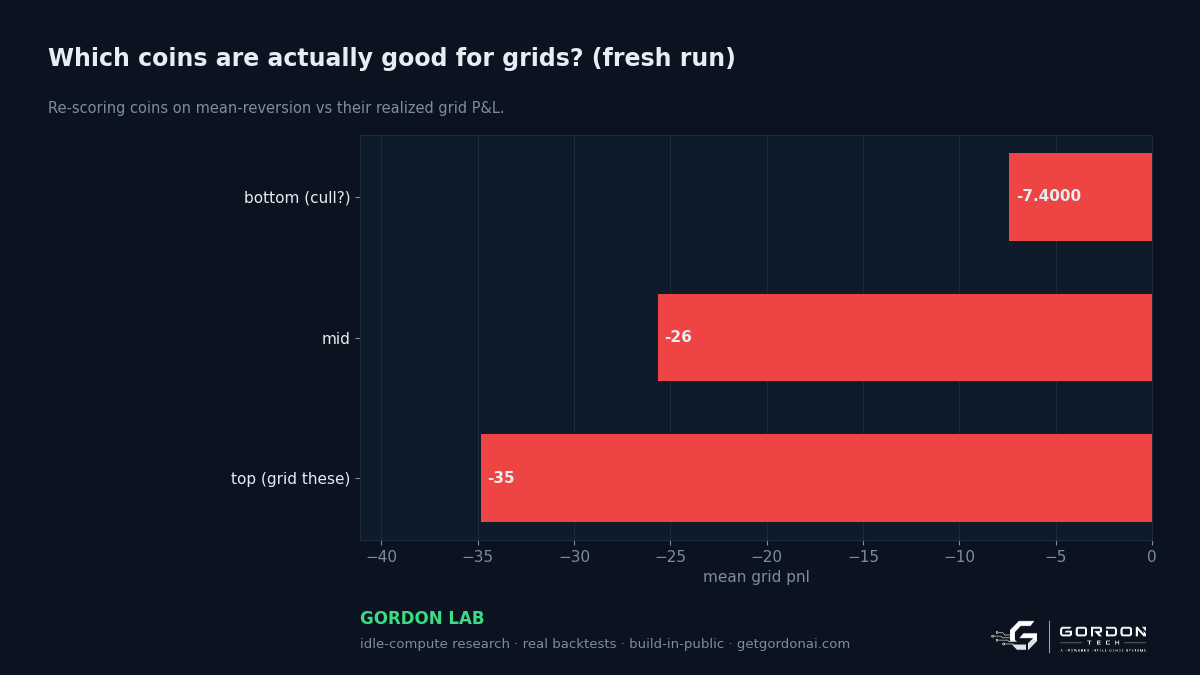
- run of 2026-09-20 — 'bottom (cull?)' leads on mean_grid_pnl: -7.40
Is a simple trend filter better than the grid?
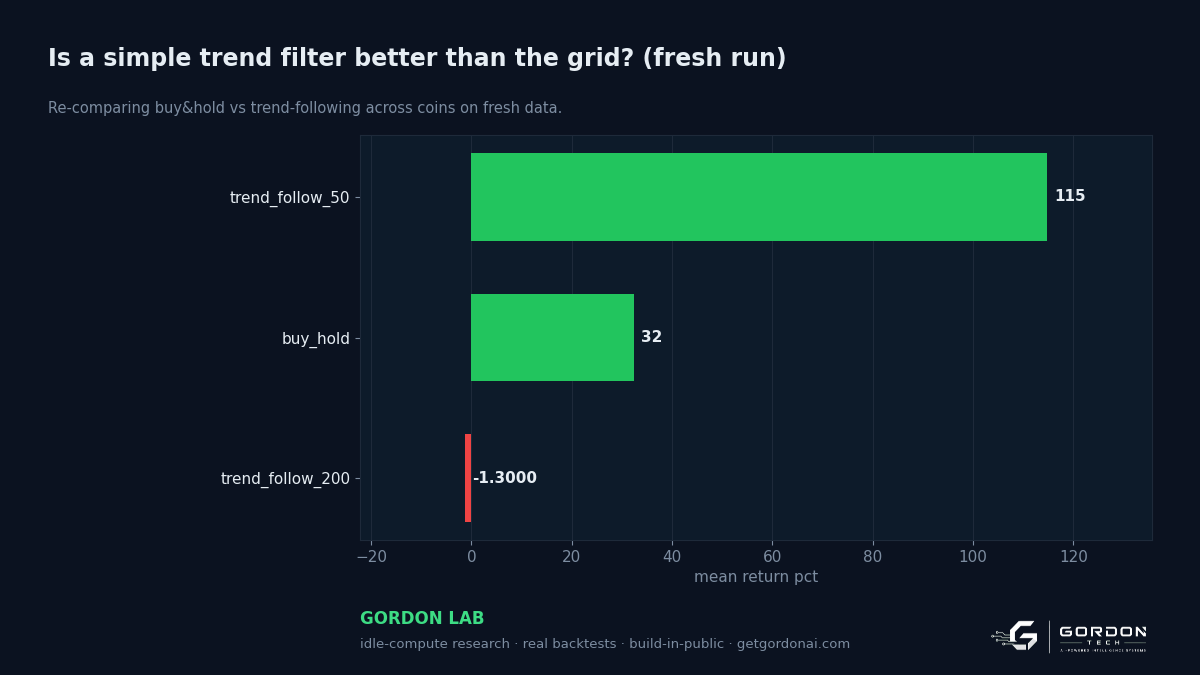
- run of 2026-09-21 — 'trend_follow_50' leads on mean_return_pct: +115
Auto-published weekly by Gordon Lab. Each entry is a real backtest or model run on real market data; methods and full result tables live in the lab archive. This is research, not financial advice.